When homeowners insurance covers mold remediation

Most home policies leave out mold cleanup and testing after damaged items are removed, Texas regulators say. Sort your water source and flood rules.
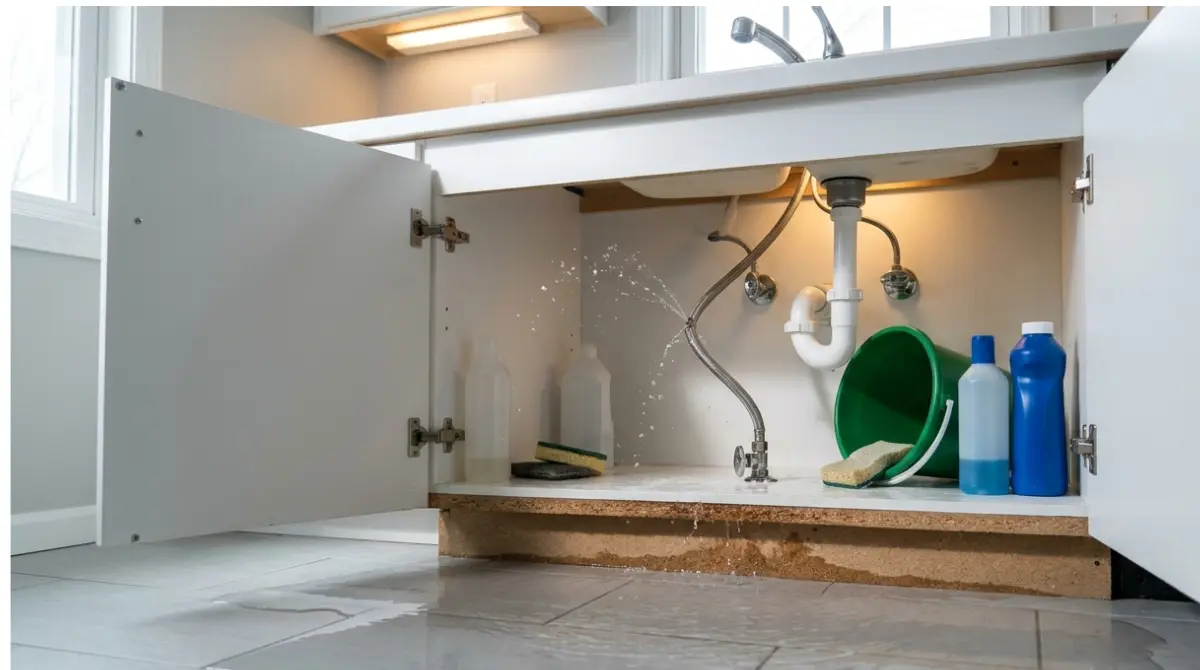
Table of Contents
Homeowners insurance usually pays for mold that grows from sudden, accidental water damage, such as a burst pipe, an overflowing toilet or a broken washer hose, and usually does not pay when the water seeped in slowly or came from a flood (Texas Department of Insurance). No claim decision has to be made tonight, so the first job is stopping the water and drying the area, ideally within 24–48 hours of the leak (EPA’s mold guide).
Most standard homeowner policies exclude damage caused by mold, fungi, rust or rot, because insurers generally treat mold as a home maintenance issue (Washington Office of the Insurance Commissioner). Coverage comes back mainly when mold follows a covered water loss. Even then, some insurers pay only a limited amount for mold, and more coverage may be available by adding a mold endorsement.
Start with where the water came from
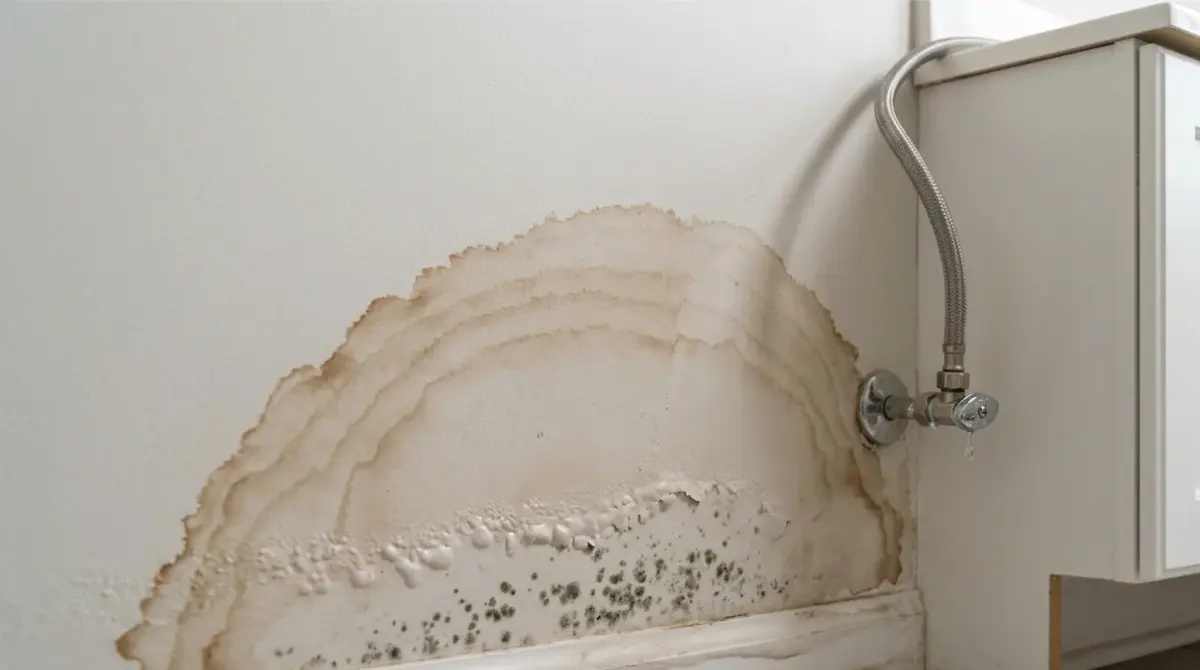
A washer hose that bursts overnight and a toilet seal that seeps for a month can soak the same subfloor and get opposite answers from the same policy. The water’s source sorts most claims.
| Where the water came from | Policy that usually responds | What regulator guidance says |
|---|---|---|
| Burst pipe, toilet overflow or broken washer hose | Homeowners or renters policy | Sudden, accidental water damage is usually covered, and mold that develops on a damaged item is covered with it |
| Slow leak or seepage | Homeowners policy | Usually not covered, mold included; Texas HO-A policies generally exclude continuous or repeated leakage |
| Mold with no sudden water event behind it | Homeowners policy | Insurers generally treat mold as a maintenance issue, and most standard policies don’t cover it |
| Backup from a sewer, sump or drain | Water backup endorsement, if you added one | Homeowners policies don’t typically cover backup; the endorsement does, and it still excludes floods |
| Floodwater | Separate flood policy | Home policies don’t cover floods; flood policies cover mold only when you acted to limit it, unless you couldn’t reach the house |
Sources: TDI water and mold coverage, Texas Attorney General, Washington insurance commissioner, Florida endorsement guide, FEMA flood claim steps.
Hidden water damage has its own clock: it usually has to be reported within days of when you first see it (TDI claim tips). Water that came up through a basement floor or out of a failed sump pump follows separate rules, sorted by source in what insurance covers for basement water.
Paying for the damage vs paying for the mold cleanup
Replacing wet drywall and paying for a mold job are separate line items, and the second is the part many policies leave out. Most home policies don’t include mold cleanup and testing after a damaged item is removed, though your company may let you add coverage for cleanup caused by a covered loss (TDI coverage tips). When Texas rewrote its standard homeowner forms in 2002, the new endorsement put the gap in one line: “We do not cover the cost for remediation, including testing of ensuing mold” (TDI endorsement HO-161A).
Remediation in Texas starts with an assessment before any work and ends with confirming the mold won’t return, and many HO-A policies either leave it out or cap it (Texas AG mold guidance).
Buying more coverage looks like this in Florida: a property mold endorsement raises the mold limit to $25,000 or $50,000, with other limits at some companies, because testing and removal can exceed a standard policy’s limit (Florida Insurance Consumer Advocate). What the work tends to cost room by room is in mold remediation cost by room.
Does flood insurance cover the mold that follows?
In one appeal FEMA published, mold confirmed about five months after a September 2019 flood was excluded, and FEMA agreed with the insurer’s denial even though the owners said they had finished mitigation promptly (FEMA appeal decision B15). Starting the drying as soon as it is safe to go back in puts a flood claim on firmer ground.
Flood insurance through the National Flood Insurance Program covers mold that follows a flood only when the policyholder acts to limit it. Minimizing the growth and spread of mold is the policyholder’s job, and NFIP policies won’t cover mold damage when the policyholder fails to act. Mold damage may still be covered when officials banned entry to the area or floodwater kept the owner from reaching the house (FEMA flood claim steps).
Before cleanup, photograph and video the damage, and talk to your flood adjuster before signing any remediation contract. A storm can bring both a homeowners claim and a flood claim, each with its own adjuster (FEMA’s claim page). The cleanup itself is laid out in mold cleanup after flooding.
Protect the claim while you dry the house
Work through these steps in order, from TDI’s water damage steps:
- Stop the water at the main valve or at the shutoff under the sink or near the appliance.
- Remove standing water and start drying, since mold can begin growing within a day of a leak.
- Move wet items to a dry room, and pull up wet carpets and rugs.
- Tell your insurance company as soon as possible.
- Photograph or video the damage before any repair, and keep damaged items until the adjuster has seen them.
- Make only temporary repairs, such as a tarp on the roof, and save the receipts.
Not every patch needs a contractor or a claim. EPA’s homeowner guide uses about 10 square feet, roughly a 3-by-3-foot patch, as the size you can handle yourself in most cases (EPA cleanup guidance), and when DIY mold removal fits walks through that call.
Safety: A heating or cooling system you know or suspect is contaminated with mold can spread it through the house, so leave it off. Growth larger than about 10 square feet or heavy water damage moves the job to EPA’s professional remediation guidance, and sewage water calls for a professional experienced with contaminated water (EPA homeowner guidance).
Texas rules: licensed remediators and a certificate
In Texas, mold work paid for by insurance leaves a paper trail, and that paper matters later. Non-exempt mold assessors and remediators need a Texas Department of Licensing and Regulation license, and one person can’t do both jobs on the same project. An assessment is required before remediation starts, so check your policy for whether the settlement should include its cost. Your insurer can suggest companies but can’t require a specific one, and within ten days of finishing, the remediator must give you a certificate of mold remediation showing whether the underlying cause was fixed (Texas Attorney General mold remediation page).
That certificate counts at renewal. Texas law bars an insurer from making an underwriting decision based on previous mold damage or a mold claim when a certificate shows, with reasonable certainty, that the cause was remediated, and a seller must give the buyer copies of certificates from the previous five years (Texas Senate analysis of HB 1328).
Property claims are generally recorded in the national CLUE database. The attorney general’s page adds that you don’t have to report mold you pay to remediate yourself, though a policy may require reporting water damage within a set time, generally 30 days (attorney general’s CLUE section). Whether to file is your decision with your agent; TDI takes insurance complaints and answers questions at 800-252-3439.
Does homeowners insurance cover black mold?
Coverage guidance sorts mold by the water’s source, and none of the state regulator pages on mold coverage single out black mold. CDC says it isn’t necessary to identify the type of mold in a home and that all molds should be treated the same for health risks and removal (CDC mold facts). Symptoms belong with a doctor.
Check your policy’s mold lines, then call your agent
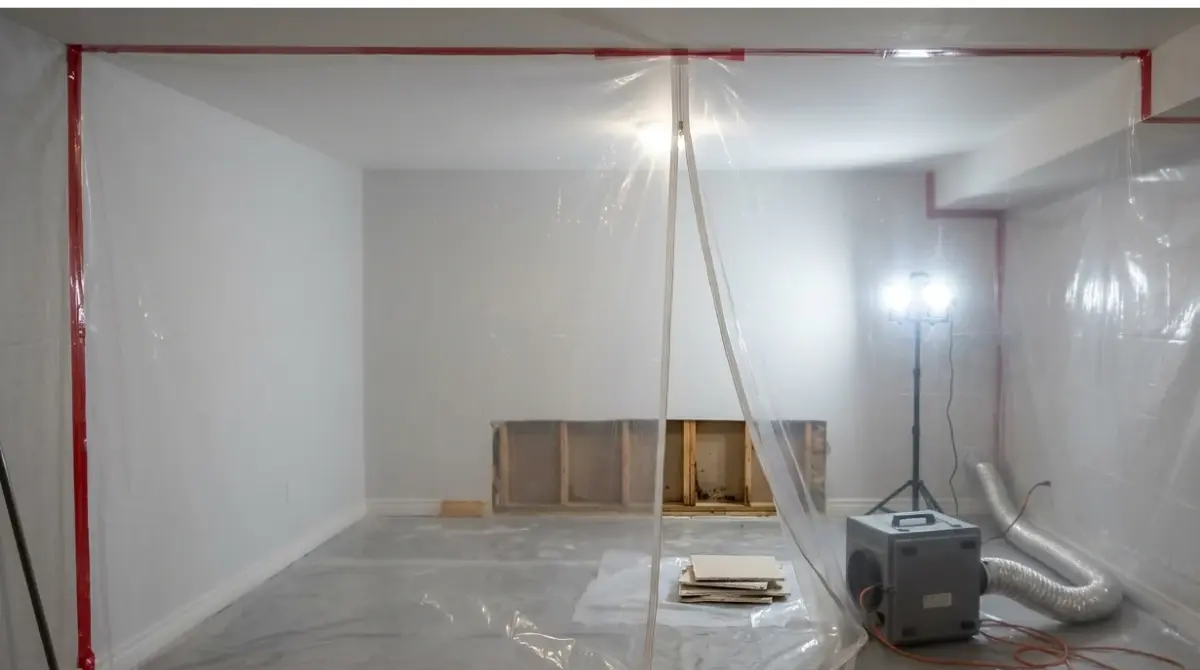
The exclusions and the declarations page hold most of the answer. Search the policy PDF for “mold” and “fungi” to find the exclusion and any exception for mold caused by a covered water loss, then check the declarations page for a separate mold limit. Look through the endorsement list as well for a mold or water backup endorsement; endorsements change the policy, so read each one in full (Florida’s endorsement guidance).
Then call your agent with three questions: are mold cleanup and testing covered after a covered loss, or only the damaged materials; how many days do you have to report hidden water damage; and is a mold endorsement available, at what limit. The insurer decides the claim under its policy wording. For the whole path from finding mold to confirming it’s gone, start with the mold remediation diagnostic plan.